Notarization Checklist for Property Closing: 2026 Guide
Notarization Checklist for Property Closing: 2026 Guide
A notarization checklist for property closing is defined as a structured verification process that confirms signer identity, document completeness, and legal signatures before any real estate transfer can be recorded. 32% of real estate transactions experienced closing delays in 2024, with documentation gaps and notarization errors among the leading causes. Title problems alone account for 25% of all closing delays. Getting your closing checklist right before you sit at the table is the single most effective way to protect your timeline and your investment. Premier Notary & Apostille Services has processed over 1,900 documents and holds a 5-star Google rating, making it a trusted resource for buyers and real estate professionals who need notarization done correctly the first time.
1. Which documents require notarization at property closings
Nearly every document transferring ownership interest must be notarized for county recorder acceptance. A missing notarization causes outright rejection, not a simple correction. Knowing which property closing documents need a notary stamp before you arrive prevents last-minute scrambles.
Documents that require notarization:
- Warranty deed: Transfers full ownership with seller guarantees. Notarization is mandatory for recording.
- Quitclaim deed: Transfers whatever interest the grantor holds, often used in divorces or family transfers. Must be notarized.
- Grant deed: Common in California and other western states. Requires notarization for county recording.
- Deed of trust: Secures the lender’s interest in the property. Notarization is required in most states.
- Mortgage documents: The promissory note and mortgage instrument both require notarized signatures in many jurisdictions.
- Affidavits: Affidavits of title, survivorship, or heirship are supporting documents that frequently require notarization to be legally valid.
- Power of attorney: If a party cannot attend closing, a notarized power of attorney authorizes a representative to sign.
Understanding the legal difference between an acknowledgment and a jurat matters here. An acknowledgment confirms the signer appeared and voluntarily signed. A jurat requires the signer to swear or affirm the document’s contents are true. Using the wrong notarial act on a deed causes rejection at the recorder’s office. Your title company or real estate attorney should specify which act applies to each document on your closing checklist.
2. What identification and signer verification is required
Proper ID is the most common cause of notarization delays at real estate closings. The name on your ID must match the name on every document you sign, character for character. A middle initial present on the deed but absent on your driver’s license is enough for a notary to pause the appointment.
Acceptable government-issued photo IDs typically include:
- Driver’s license (current, not expired)
- U.S. passport or passport card
- State-issued ID card
- Military ID
- Permanent resident card
State requirements vary. Some states allow a credible witness to vouch for a signer who lacks acceptable ID. That witness must personally know the signer and have no financial interest in the transaction. Relying on a credible witness adds time and complexity, so bring a current, matching ID instead.
The notary’s legal role goes beyond checking a photo. The notary must verify the signer appears willing, understands what they are signing, and is not under duress. If a signer seems confused or coerced, the notary is required to stop the appointment.
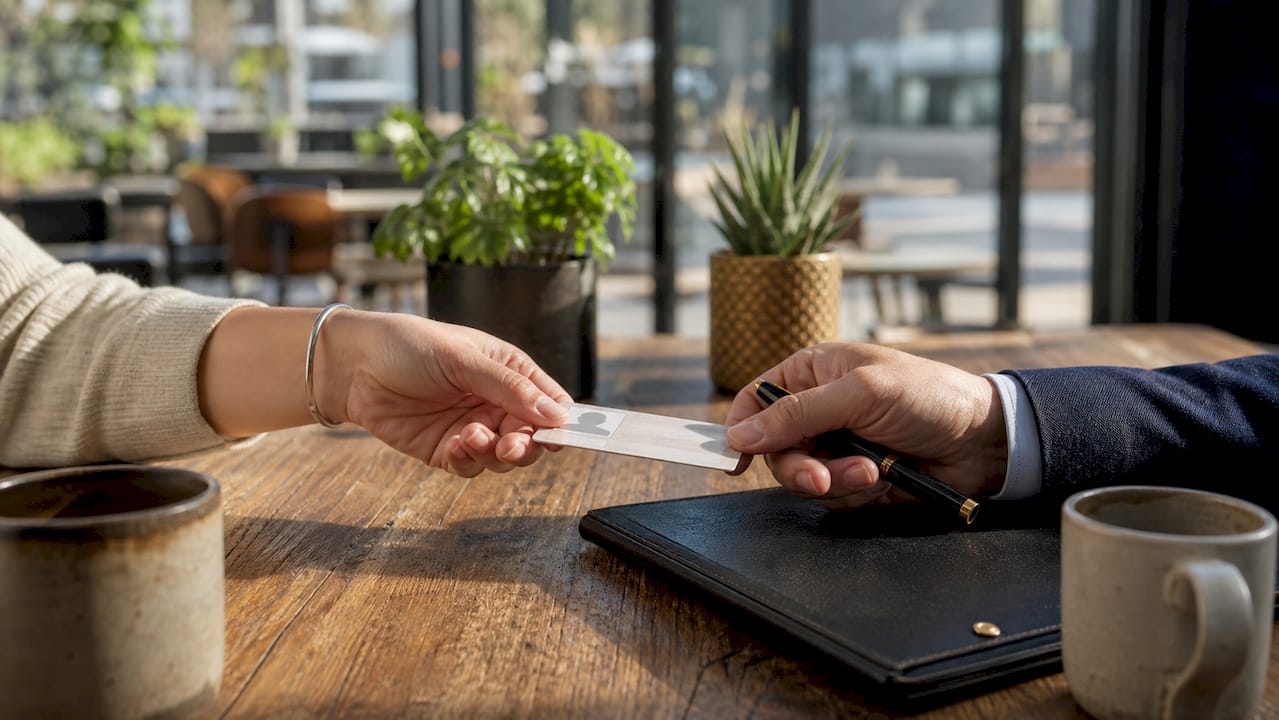
Remote online notarization (RON) is now permitted in most states. RON uses audio-visual technology and identity-proofing tools to verify signers who cannot appear in person. Not every lender or title company accepts RON for all closing documents, so confirm acceptance before scheduling.
Pro Tip: Bring two forms of ID to closing. If your primary ID has a discrepancy, a backup document can help the notary verify your identity without rescheduling.
3. How much notary fees typically cost at closing
Notary signing agents typically charge between $75 and $200 per appointment for full closing packages. That range reflects the volume of documents in a standard real estate closing, not a per-signature fee. Evening and weekend appointments often carry higher fees, sometimes above the standard range.
Key fee facts to know:
- Fees are usually paid by the buyer or rolled into closing costs
- Some lenders or title companies include notary fees in their service charges
- Mobile notary services, where the notary travels to you, typically cost more than office appointments
- Same-day or rush notarization services carry a premium
Budget for notarization as a fixed line item in your closing costs. Treating it as an afterthought leads to surprises on your final settlement statement. Ask your title company or lender early in the process whether notary fees are included or billed separately. For buyers working through a closing document workflow, understanding every cost category upfront prevents delays caused by funding shortfalls on closing day.
4. The Closing Disclosure and timing requirements
The Closing Disclosure must be delivered to the buyer at least 3 business days before closing under TRID rules (the TILA-RESPA Integrated Disclosure rule). Any material change to the loan terms resets that 3-day clock. That reset can push your closing date back by several days, affecting moving schedules, rate locks, and seller agreements.
Review the Closing Disclosure the moment you receive it. Compare every figure to your Loan Estimate. Flag discrepancies in fees, interest rate, or loan terms immediately. Your lender must correct material errors before closing can proceed. Catching a fee change on day one of the 3-day window gives you time to resolve it. Catching it on closing morning does not.
5. Common notarization checklist mistakes that delay closings
Documentation errors are preventable. The most costly mistakes share one trait: they are discovered at the closing table, not before it.
- Expired or mismatched ID. A driver’s license that expired last month or a name spelled differently on the deed and the ID stops the appointment immediately.
- Blank fields on notarized documents. Notaries must never notarize documents with blank fields in the main body. Blank spaces allow post-signing alterations, which is why recorders and lenders reject them outright.
- Missing witnesses in required states. States like Florida and Georgia require two disinterested witnesses on certain deeds, in addition to a notary. Forgetting witnesses causes recording rejection and forces a re-signing.
- Incomplete documents brought to the notary. A document with missing dates, unsigned lines, or unfilled legal descriptions cannot be notarized. Complete every field before the appointment.
- Late document review. Reviewing documents the night before closing leaves no time to fix errors. A final review at least 48 hours before closing catches missing notarizations, stale payoff figures, and name mismatches while there is still time to act.
- Conflict-of-interest notaries. Notary employees of title companies or lenders may be prohibited from notarizing certain documents due to conflict-of-interest policies. Verify your notary’s eligibility for each document in advance.
- Wrong notarial act. Using an acknowledgment when a jurat is required, or vice versa, invalidates the notarization. Confirm the required act for each document with your attorney or title officer before closing.
Pro Tip: Create a document checklist with each item’s required notarial act, witness count, and ID requirement listed next to it. Review it 48 hours before closing, not the morning of.
6. How to prepare documents 30 days before closing
Starting document preparation at least 30 days before closing gives you time to resolve title exceptions, correct name discrepancies, and schedule the right notary. Title searches take 10–14 business days on average. Starting late compresses every step that follows.
Gather all property closing documents in a single folder, physical or digital. Confirm each document’s notarization requirements with your title company or real estate attorney. Check that every signer’s name appears identically across all documents and IDs. If a name discrepancy exists, an affidavit of identity can resolve it before closing day.
Schedule your notary appointment as soon as your closing date is confirmed. For real estate notarization, experienced notaries familiar with deed and mortgage documents reduce the risk of procedural errors. Verify the notary’s commission status and confirm they carry errors and omissions insurance. Both protect you if a notarial error surfaces after recording.
7. How remote online notarization changes the process
Remote online notarization is now authorized in the majority of U.S. states. It allows signers to complete notarization over a secure audio-visual platform without traveling to a physical location. The notary verifies identity using knowledge-based authentication questions and credential analysis technology.
RON works well for buyers relocating from out of state or sellers who have already vacated the property. The process produces a tamper-evident electronic document with an embedded digital certificate. Not every county recorder accepts electronically notarized documents, and not every lender approves RON for mortgage documents. Confirm acceptance with your title company, lender, and county recorder before choosing this path.
Key Takeaways
A complete notarization checklist for property closing requires verified IDs, fully completed documents, correct notarial acts, and state-specific witnesses to prevent recording rejection and closing delays.
| Point | Details |
|---|---|
| Start 30 days early | Begin gathering documents 30 days out to resolve title exceptions and name mismatches before closing day. |
| Match IDs to documents | Every signer’s name must appear identically on their government-issued ID and all closing documents. |
| Complete all fields first | Never bring a document with blank fields to a notary appointment. Fill every line before the meeting. |
| Know your state’s witness rules | States like Florida and Georgia require two disinterested witnesses on certain deeds, beyond the notary. |
| Review 48 hours before closing | A final document check two days out catches errors while there is still time to correct them. |
What I’ve learned from watching closings go wrong
The closings that fall apart rarely fail because of big legal problems. They fail because of small, fixable details that nobody checked. An expired ID. A middle name on the deed that does not appear on the driver’s license. A deed of trust with one line left blank.
Working through hundreds of real estate notarizations, the pattern is consistent. Buyers and agents who treat the notarization checklist as a formality are the ones who reschedule. The ones who treat it as a legal verification process, with the same attention they give the purchase price negotiation, close on time.
The 48-hour review rule is the single most effective habit I have seen. Reviewing every document two days before closing, not the morning of, gives you a real window to fix problems. A missing witness can be arranged. A name discrepancy can be addressed with an affidavit. A wrong notarial act can be corrected before the appointment. None of those fixes are available at 9:00 AM on closing day.
One more thing most buyers do not think about: verify that your notary has no conflict of interest before the appointment. A notary employed by your title company may be restricted from notarizing certain documents in that transaction. Finding that out at the table costs you a day, sometimes more. Ask the question in advance.
The buyers who close without delays are not lucky. They are prepared.
— Premier
Premier Notary & Apostille Services: real estate notarization made straightforward
Property closings involve a high volume of documents, each with specific notarization requirements. One missed step can delay recording and push back your move-in date.
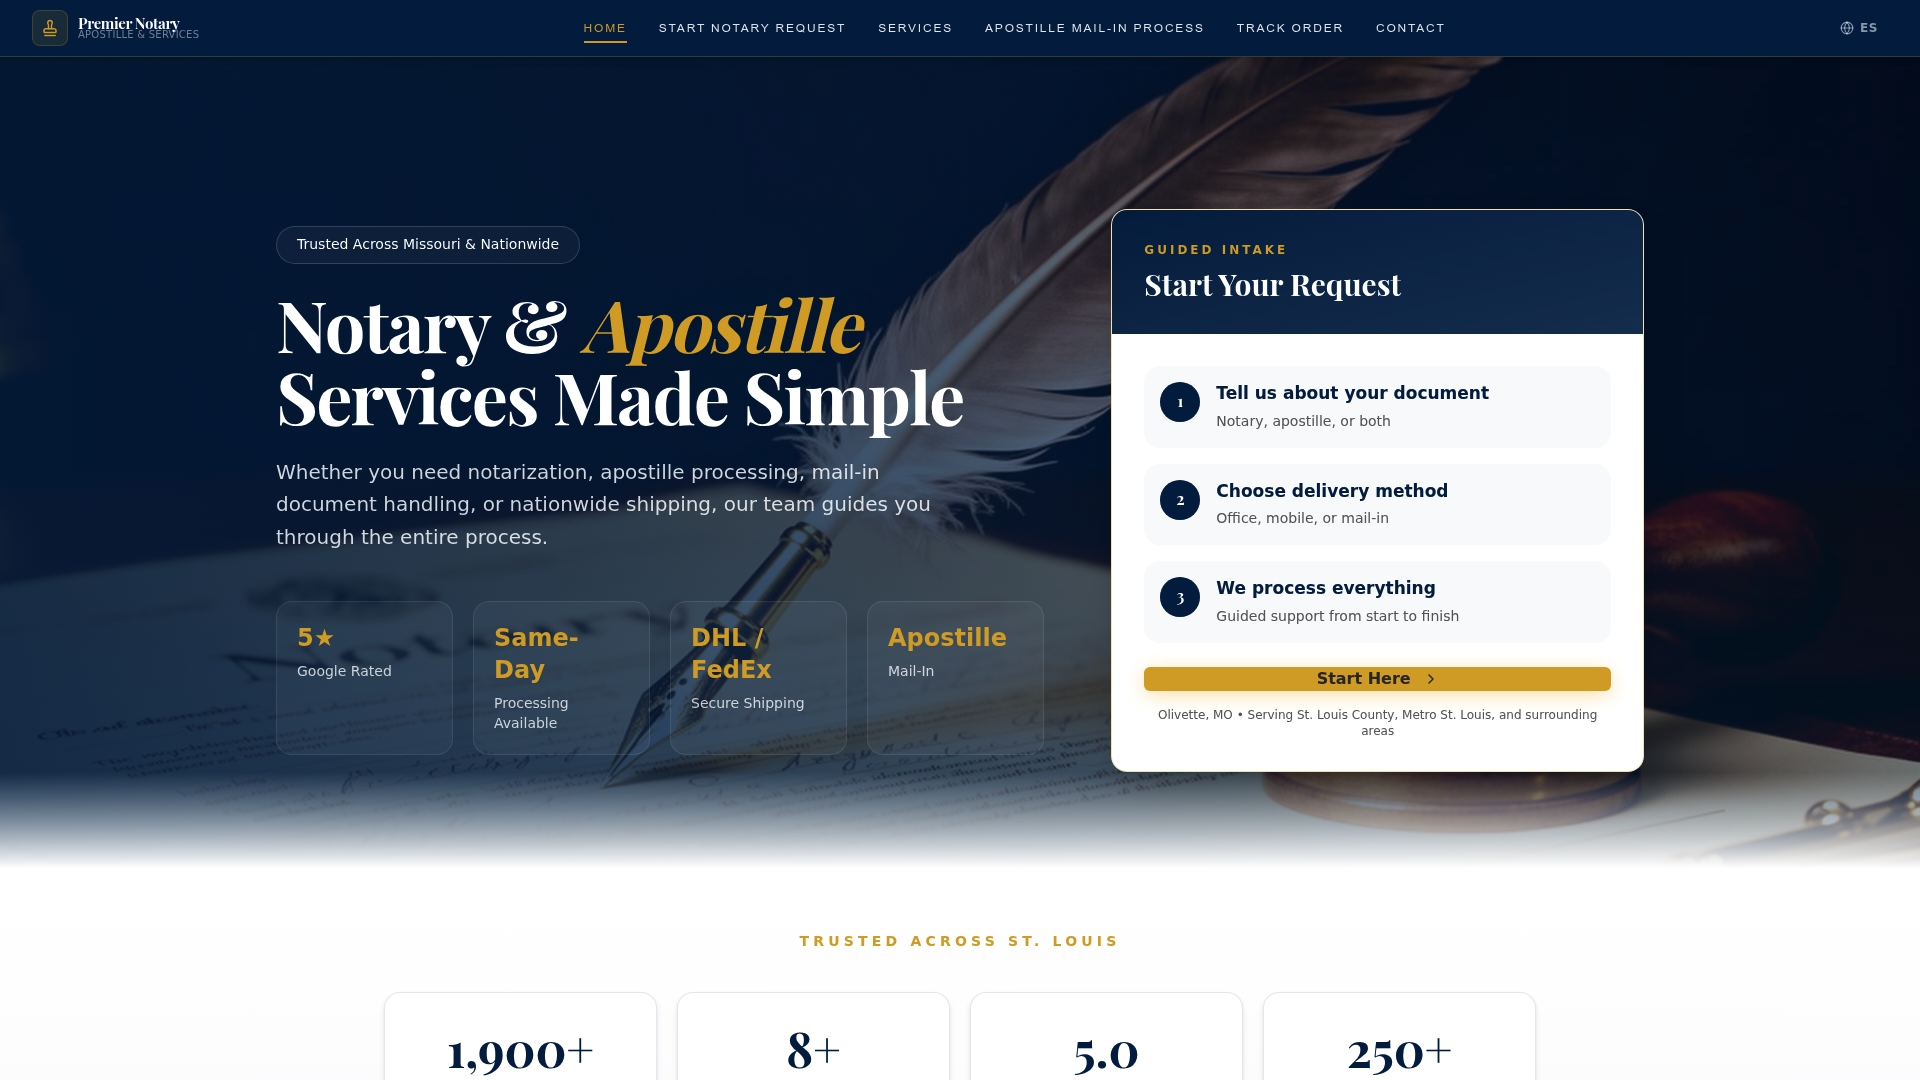
Premier Notary & Apostille Services specializes in real estate document notarization, with same-day processing options and a guided intake process that confirms every document is complete before the appointment begins. With over 1,900 documents processed and a 5-star Google rating, the team brings the accuracy and speed that real estate closings require. Transparent pricing means no surprises on your settlement statement. Schedule your appointment directly and get your closing documents notarized correctly the first time.
FAQ
What documents need notarization at a property closing?
Deeds (warranty, quitclaim, and grant), deeds of trust, mortgage documents, affidavits, and powers of attorney all require notarization. Missing a notarization on any of these causes rejection at the county recorder’s office.
How much does a notary cost for a real estate closing?
Notary signing agents typically charge between $75 and $200 per appointment for a full closing package. Evening, weekend, and mobile appointments often cost more.
What ID do I need for notarization at closing?
Bring a current government-issued photo ID such as a driver’s license, U.S. passport, or state ID card. The name on your ID must match the name on every document you sign exactly.
Can I use remote online notarization for my closing?
Remote online notarization is permitted in most U.S. states, but not every lender or county recorder accepts electronically notarized documents. Confirm acceptance with your title company and lender before scheduling a RON appointment.
What are the most common notarization mistakes at closings?
The most frequent errors are expired or mismatched IDs, blank fields left on documents, missing state-required witnesses, and using the wrong notarial act. A final document review 48 hours before closing catches most of these before they cause delays.